INFINITE ACCOUNTANT · FOR UK CHARTERED PRACTICES AI review of non-audit statutory accounts, under NDA

Up to £700 of manager and partner time back on every set of accounts you sign.

Infinite Accountant does the manager’s review of each file, so it reaches the partner already reviewed. The partner still signs.

Every point arrives in writing, largest first, traced to the accounts, the working papers or the trial balance. Alongside it comes a short commercial brief on the client for the partner, and written review notes for whoever prepared the file.

Built and used inside Jack Ross Chartered Accountants, a Manchester practice founded in 1948. Professional, regulatory and PI responsibility stays with your firm and the signing partner.

  1. On each set of accounts up to £700

    Three manager hours at £150 and one partner hour at £250 that the file no longer needs.

  2. For each partner, each year £105,000

    A partner signing 150 sets a year at £700 a set. For a ten-partner firm that is 6,000 hours, or 800 working days.

  3. What a review manager costs £60kto£80k

    A year of one qualified review manager, with NIC, pension and overhead. That is the cost you avoid for each post you no longer need to fill.

The first two figures value review time at charge-out rates. They turn into profit when you bill the hours to other work or leave a manager’s post unfilled, and the calculator lets you put in your own partners, files, rates and hours.

What you get

What changes for the firm

For practice owners

Most firms can find juniors and can win work. The hard part is finding a good review manager, paying what they now ask and keeping them, and in many firms that sets the limit on how much work gets signed. Infinite Accountant does that manager’s review on every file.

  • Less rides on hiring a review manager.

    A review manager costs £60,000 to £80,000 a year once NIC, pension and overhead are in. With the first review done on every file, the number of sets you can sign depends much less on whether you can fill that post and keep it filled.

  • Files reach the partner already reviewed.

    The points come in writing, largest first, each with its reference and the cell it came from, so the partner is checking a review rather than doing one. Our model assumes one partner hour saved on each file. Higher-risk files stay partner-led.

  • The same review on every file.

    Every file is reviewed to the same standard whoever prepared it and whichever partner signs it, and the written record is there when ICAEW or ACCA quality monitoring comes round.

  • Room to take on more work.

    A file no longer has to wait for a gap in one manager’s diary before it reaches the partner, so less work in progress sits unbilled, and taking on new engagements depends less on recruiting.

  • A fee conversation from the file.

    Where the file shows a tax planning point, a capital allowances or R&D claim, or another service the client could use, the Partner Pack says so, puts a figure on it and suggests how to raise it.

  • Proper review notes for juniors.

    Preparers get a written reason for every point, with the FRS reference and the working paper, on every file. That is the feedback the best managers give, and it no longer depends on which manager a junior happens to work for.

The arithmetic

Where the £700 comes from

Per file · per partner · per firm

In a mid-tier practice most statutory files are reviewed twice, first by a manager and then by a partner. Infinite Accountant does the manager’s review and shortens the partner’s, which in our model frees up to four hours on each file. What those hours are worth depends on what you do with them.

Per set of accounts

Manager time plus partner time

  1. Manager review £450

    Three hours at a £150 manager charge-out rate.

  2. Partner review £250

    One hour at a £250 partner rate, because the partner reads a file that has already been reviewed.

  3. Each file £700

    Up to £700 of review time on each file. It reaches profit when the hours are billed to other work, a hire is avoided or more files go through.

Your firm

Put in your own numbers.

Change the partners, files, rates and hours to match your firm. The result shows the review time released in pounds, hours and working days, and the portfolio box scales it across a group of practices.

Firm assumptions
including junior partners
non-audit stat accounts · typical 80-200
your hourly charge-out rate
manager review time no longer needed
partner review time saved
for groups · scales the firm totals
Your estimate

Review time released each year

1,050,000

6,000 hours · 800 working days of review time

Per set of accounts
£700
Per partner, each year
£105,000
Over three years
£3,150,000
Over five years
£5,250,000

Figures shown for 1 practice(s). The portfolio box scales the yearly, hours, working days and multi-year totals; the per-file and per-partner figures stay as they are. This is review time at charge-out rates, not a profit forecast: what reaches profit depends on how much of the work you move across, the hires you avoid and the extra work you take on. Rates are held flat, and a working day is 7.5 chargeable hours.

Sample output

What a review looks like

One file · one run

The preparer uploads the file and Infinite Accountant returns two documents: review notes for the preparer and a commercial brief for the partner. Each figure in each point traces back to a file, sheet and cell. The example below uses synthetic data.

infinite-accountant · engagement #A482 Example Ltd · FY 26 · synthetic data Running
  1. read trial_balance.xlsx · 1,284 rows · OK
  2. match draft_accounts.pdf · 38 pages · OK
  3. check FRS 102 disclosure matrix · 42 / 42 · OK
  4. point 1 Finding · 01 Deferred tax not recognised on fair-value uplift. source TB!I47 → Draft p.14 §12.3 · amount £2,400
  5. point 2 Finding · 02 Corporation tax payable understated at marginal-relief boundary. source TB!C22 → CT600 Box 435 · amount £840
  6. point 3 Finding · 03 Related-party disclosure absent. Director loan cleared year-end. source TB!K88 → FRS 102 §33.9 · amount £16,400
  7. point 4 Finding · 04 Employer NIC not accrued on director bonus declared post year-end. source TB!D31 → payroll YE · amount £3,200
  8. point 5 Finding · 05 Capital allowances missed on integral features inside the recent office fit-out. source WP!CA-2 → CT600 Box 770 · opportunity £4,800
  9. point 6 Finding · 06 Going-concern review flagged; current-liabilities ratio requires documented assessment and possible disclosure. source Directors' report → FRS 102 §3.8 · disclosure only
  10. point 7 Finding · 07 Prior-period accruals restatement not separately disclosed as a comparative adjustment. source TB!J08 → FRS 102 §10.23 · amount £1,900
  11. done Review complete. 7 points, one of them a fee opportunity · preparer pack and partner pack produced as branded PDFs.
  • 01 / Evidence

    Every point is source-cited.

    Each figure traces back to file, sheet and cell, so the partner can check any point against the evidence.

  • 02 / Coverage

    Accounts, disclosures and tax.

    Trial balance to statutory accounts, the corporation tax computation, and disclosures checked against FRS 105, FRS 102 and, where it applies, IFRS.

  • 03 / Priority

    Largest points first.

    Points are ordered by quantitative and qualitative materiality, and the full log stays available for anyone who wants to read it.

  • 04 / Second look

    A second pass on riskier files.

    Higher-risk files get an adversarial pass, and a consistency check checks that the figures agree across every part of the review.

  • 05 / One run

    Both packs from one run.

    The file is read, reviewed and both packs produced in one run, so the partner reads a finished brief.

  • 06 / Your systems

    Works with what you use.

    It reads files from Xero, CCH, IRIS and Sage and returns branded PDFs in your house style. Nothing is installed and nothing moves platform.

    • Xero
    • CCH
    • IRIS
    • Sage
Output

Two documents from every run

Preparer · Partner

Every run produces two documents, one for the person who prepared the file and one for the partner who signs it. A good manager’s review does both jobs: it says what has to change, and it notices what the client might need next.

Pack I

The Preparer Pack

For the person who prepared the file.

Each point is explained in full sentences: what is wrong, why it matters, the FRS reference and the working paper that shows it. It reads like a good manager’s review notes.

  • The reason written out for every point
  • Every figure traced back to file, sheet and cell
  • FRS 105, FRS 102 or IFRS references on every point
  • Notes tied to the client file the preparer worked on

Review notes on every file they prepare.

Pack II

The Partner Opportunities Pack

For the partner signing off.

A commercial read of the client, taken from the file itself. Where the file shows a tax planning point, a capital allowances or R&D claim, or another service the client could use, the pack says so, puts a figure on it and suggests how to raise it.

  • Tax planning points with a figure and a working-paper reference
  • Other services the file points to: VAT, R&D, payroll, advisory
  • Risk signals from the file, sized against materiality
  • A suggested opening line for each conversation

Something to discuss with the client wherever the file shows it.

One point, traced

What a single point looks like

Both packs are built from points like this one. The numbers are synthetic, but the structure is the real one: the reason, the standard it rests on, the exact cell it came from and the amount involved, so every point can be checked before anyone signs.

  1. Finding

    Deferred tax not recognised on a fair-value uplift.

  2. Why it matters

    The tax charge is understated and distributable reserves are overstated in the draft.

  3. Standard

    FRS 102, Section 29: deferred tax arises on revaluation gains.

  4. Source

    TB!I47 → Draft p.14 §12.3, which is the file, sheet and cell, so the evidence is two clicks from the point.

  5. Amount

    £2,400, above the engagement’s reporting threshold, so it leads the pack.

  6. For the partner

    A one-line adjustment with the evidence attached, for the partner to check before signing.

Who built it

Built by a partner, not a vendor

Manchester · est. 1948
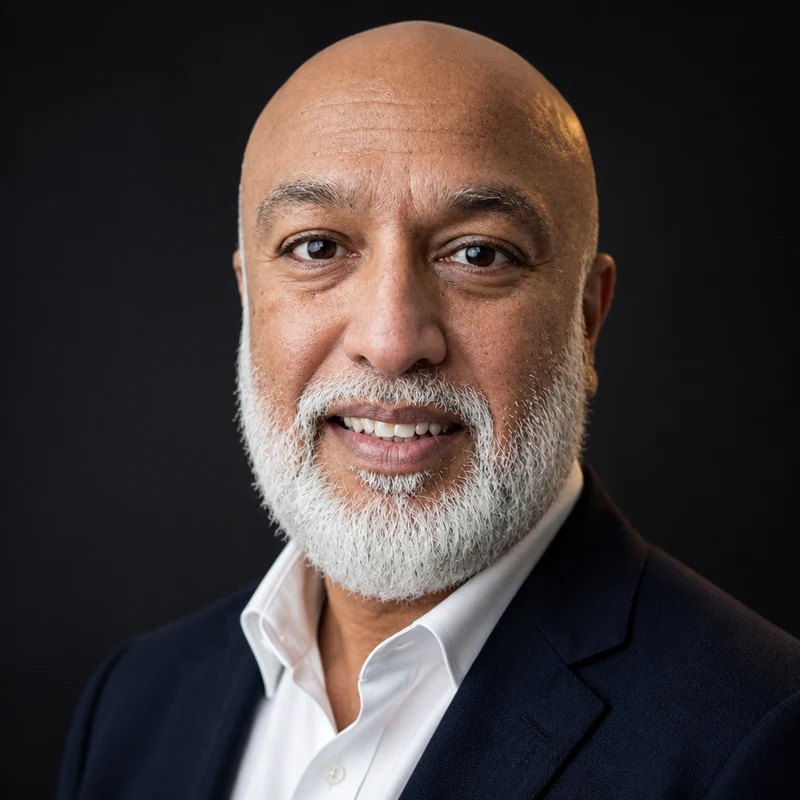
Umar Memon, Managing Partner

Umar Memon built Infinite Accountant. He is a chartered accountant and the Managing Partner of Jack Ross in Manchester, a practice founded in 1948, and the firm runs its own statutory files through it every week.

“AI can surface the evidence. The partner still signs.“

Umar Memon · Managing Partner · writes The Partner Still Signs

Safeguards

What stays with your firm

Sign-off · Data · Materiality · Risk

The partner signs, the firm keeps control, and the safeguards are agreed in writing before any file is shared.

Controls documented per firm Reviewed quarterly

  1. i.

    Partner sign-off. Sign-off stays with the qualified partner. Professional, regulatory and PI responsibility stays with your firm and the signing partner, and your ICAEW or ACCA and Companies Act obligations do not change.

  2. ii.

    Client data. Client files are processed under your firm’s existing confidentiality obligations, UK GDPR and, where it applies, EU data-protection law. Client data is not used to train third-party models. Retention and deletion are agreed with each firm in writing before onboarding, a Data Processing Agreement comes with the invitation, and penetration testing and SOC-aligned controls are documented for due diligence.

  3. iii.

    Materiality. Points are ordered by quantitative and qualitative materiality, the full log stays available, and a consistency pass checks that the figures agree across every part of the review.

  4. iv.

    High-risk files. Files with going-concern indicators, complex groups or new clients stay partner-led by default and get an extra adversarial pass for disclosure gaps a single pass could miss.

Try it on your own file

Run a pilot on one of your completed files.

Send us one completed statutory file under NDA and we will run both packs on it. You see the points, you keep the output, and you decide whether to go further. We ask for no commitment until you have seen the output.

Request access Read the free ebook NDA signed before any file is shared · Terms agreed in writing · Xero, CCH, IRIS or Sage

For acquirers and groups of practices

  • For the PE-backed acquirer

    The client base is easier to buy than the reviewers.

    After a deal, the hard part is getting every acquired firm to review files to the same standard. Infinite Accountant puts each one on the same first review, with less reliance on any single manager and fewer review posts to recruit for, so partner time can go to growing fees.

  • Across a portfolio

    The review posts a ten-firm group avoids.

    At 1.4 review-manager posts per firm and £60,000 to £80,000 a post, a ten-firm group avoids roughly £0.8M to £1.1M a year in manager cost, about £4M to £5.6M over a five-year hold. That is a staff-cost figure, which is why it is lower than the charge-out figures in the calculator.

Questions

Questions we’re asked

Partners · Practice owners · Investors
Does the partner still sign off?

Yes, always. Infinite Accountant does the manager’s review and the qualified partner signs, so ICAEW or ACCA responsibility for that signature stays with them, and professional, regulatory and PI responsibility stays with your firm.

How accurate is it?

Every figure in every point traces back to a file, sheet and cell, so any point can be checked. We measure the points found per file and the false-positive rate against experienced manager review on our own engagements, calibrate the review for each firm during onboarding and review it every quarter. A pilot lets you make the same comparison on one of your own files.

What happens if it misses something?

Three checks run before the partner sees the pack: points are ordered by materiality with the full log kept, a consistency pass checks the figures across every part of the review, and higher-risk files get an adversarial pass for disclosure gaps. The partner’s sign-off remains the final check, and the review is there to make that check lighter.

Where do our clients’ files go, and what about GDPR?

Processing runs under your firm’s existing confidentiality obligations and UK and EU data-protection law, and no client data is used to train external or third-party models. Retention and deletion are agreed with each firm in writing before onboarding, and a Data Processing Agreement comes with the invitation. Penetration testing and SOC-aligned controls are documented for due diligence.

We already use CCH, IRIS, Xero or Sage. Does this replace them?

No. It sits alongside your production software, reads the trial balances, draft accounts, tax computations and working papers from the systems you already use, and returns branded PDF packs in your house style. Nothing moves platform.

How do junior staff learn if software does the review?

They get a written reason for every point on every file they prepare, with the FRS reference and the working paper behind it. That is the feedback the best managers give, and it no longer depends on which manager a junior happens to work for.

What does it cost?

Commercial terms are given on invitation, under NDA, and agreed in writing. A pilot runs on one of your own files before you commit to anything.

Further reading

Guides and articles

Free to read

Practical guides on reviewing statutory accounts, the FRS 102 changes, quality management and client data, with shorter articles for the people who prepare and sign the files. Umar Memon also writes about AI in accountancy at umarmemon.com.